On September 17, 2026, the SEC approved the Innovation Exemption—a conditional five-year framework letting tokenized securities venues (TSVs) trade tokenized stocks without registering as national exchanges. Tokenized stocks are no longer a crypto sideshow.
They are a regulated pathway into the deepest capital market on earth. Uniswap ripped 20% in 24 hours. Coinbase, Robinhood, and Circle led crypto-native gains. The old playbook is dead—not because blockchain replaced the NYSE overnight, but because the SEC admitted on-chain settlement is viable for National Market System equities.
The thesis is simple: stock tokenization is now the next vertical for DeFi and Wall Street, and anyone still framing this as a 2020 experiment is already behind.
Why Tokenized Stocks Are Breaking Out Now
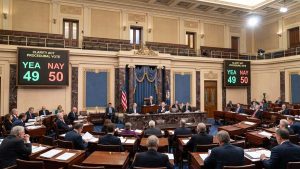
Two days before the SEC’s move, the Senate rejected the CLARITY Act by a 49-50 vote. That should have been a devastating blow for regulatory certainty. Instead, the SEC used existing authority to build administratively what Congress failed to pass.
Chairman Paul Atkins said it plainly: “The Commission is not cementing current technology as the standard of tomorrow. It is allowing the market to evolve.”
Translation: if Congress won’t legislate, the SEC will create operational precedent through temporary exemptions.
Institutional flows have been anticipating this for months. Bitcoin spot ETFs normalized regulated exposure. Stablecoins—USDC chief among them—became the settlement rail of choice for corporate treasuries. Tokenized stocks are the next logical link.
BlackRock’s BUIDL, Franklin Templeton’s on-chain money market funds, and growing tokenized treasury products have already proven that institutions will use blockchain rails when compliance is clear.
The macro backdrop—liquidity rotation, demand for yield, and regulatory arbitrage between the U.S. and Europe—makes this the moment when Wall Street blockchain stops being a buzzword and becomes a venue strategy.
Argument 1: AMMs Are Now Market Infrastructure, Not DeFi Toys
The SEC drew a surgical line: only platforms based on Automated Market Makers (AMMs) qualify. Centralized exchanges with central limit order books (CLOBs)—including Coinbase’s traditional venue—are excluded from the framework.
For years, AMMs were dismissed by TradFi as a DeFi curiosity, an inefficient mechanism that only worked for long-tail tokens with thin liquidity. The SEC just implicitly declared them valid infrastructure for NMS securities.
AMMs guarantee continuous liquidity without a designated market maker, eliminating counterparty risk outside market hours. Settlement is atomic.
Settlement risk drops to zero. For Tier 1 equities—the most liquid on the NMS—each TSV can list up to 75 symbols and trade up to 0.25% of the prior month’s average daily volume. For Tier 2, the cap rises to 250 symbols with a 2.5% limit.
-
Tier 1: 75 symbols, 0.25% ADV cap
-
Tier 2: 250 symbols, 2.5% ADV cap
-
Synthetic products: explicitly excluded
-
Smart contracts: auditable, public, deployed on permissionless networks
The Caps Are the Message
They are a risk-management mechanism designed to prevent a smart contract exploit or liquidity pool failure from destabilizing the underlying market. If a venue breaches the cap, the SEC triggers a three-month pause on that specific security. Fail fast, contain fast. That is exactly what an institutional risk analyst wants before allocating capital.
This is the Trojan horse: AMM logic enters the heart of Wall Street, wrapped in a sandbox.
Argument 2: Coinbase, Robinhood, and Circle Already Built the Product
While most traditional exchanges watch from the sidelines, three players have spent months building the infrastructure that the SEC exemption now legitimizes.
Coinbase is the clearest case. Its tokenized equity offering already includes shareholder rights and dividends comparable to the underlying stock, and CEO Brian Armstrong confirmed voting rights are “coming soon.” Goldman Sachs noted that Coinbase’s institutional custody, Coinbase Tokenize, and Base—its Ethereum Layer 2—position it to capitalize on multiple fronts. Base gives it a low-fee settlement environment with growing TVL and developer activity.

Robinhood already operates roughly 200 tokenized stocks across more than 120 countries outside the U.S. Its plan is to allow 1:1 conversion between tokens and underlying shares, plus voting rights. The obstacle: its venues use CLOBs, not AMMs. To operate under the exemption in the U.S., it will need new infrastructure or route activity through DeFi protocols on Base or another L2.
Circle is not a venue. But USDC becomes the natural settlement rail for these trades. Analysts highlight that Circle benefits from increased USDC use for settlement and collateral in tokenized markets. The stablecoin float becomes the cash leg of atomic equity settlement.
The Bear Case: “This Isn’t DeFi, It’s a Gilded Cage”
The sharpest criticism does not come from Bitcoin maximalists. It comes from DeFi builders who read the fine print and found something uncomfortable.
SEC Commissioner Hester Peirce, the agency’s most crypto-friendly voice, said it without ambiguity: “This order is not about decentralized finance.”
She is right. TSVs must use auditable smart contracts on public blockchains, but with permissioned access lists and KYC/AML requirements that distance them from permissionless DeFi ethos. Liquidity providers get a temporary exemption from dealer registration, but they do not operate in an intermediary-free environment.
Bears argue this is not the disruption tokenization promised. It is Wall Street adopting on-chain aesthetics to cut operational costs, not to decentralize access. Issuers also have an objection right: if a company does not want its shares tokenized, it can block it with a 30-day window.
The exemption is a pilot, not the end state. Atkins said this measure “must be followed by durable rulemaking.” The five-year experiment will generate operational data—volumes, security incidents, investor behavior—that informs permanent regulation. The market does not need the first iteration to be perfect. It needs it to exist. And it exists.
The $5.5 Trillion Market Starts Now
Tokenized securities are a $6.8 billion market in 2026, projected to reach $48.5 billion by 2034, a 27.8% CAGR. More aggressive forecasts see tokenized equities hitting $5.5 trillion by 2030.
But the real shift is regulatory. The SEC just said, with a five-year exemption, that blockchain infrastructure is mature enough to process securities from the world’s deepest financial system.
Not synthetic derivatives. Not products wrapped in crypto marketing. Real stocks with real voting rights and real dividends, traded in liquidity pools with auditable smart contracts.
The question is no longer whether Wall Street will tokenize. The question is which crypto-native actor will be at the table when permanent rules are written five years from now.
The Community Gets the Last Word
Is this the victory crypto waited for, or a domesticated version that strips out what made DeFi special? AMMs are no longer a niche experiment: they are regulated infrastructure for NMS securities. But permissions, caps, and issuer objection rights draw a perimeter that looks more like a free-trade zone than an open market.
Would you rather have a tokenized system with KYC and regulatory caps, or keep waiting for the permissionless decentralization that never came to Wall Street? The debate is open. This time, the SEC is listening.