

TL;DR:
- Saylor proposed that the crypto industry prioritize building products and reaching 50 million users before relying on new legislation.
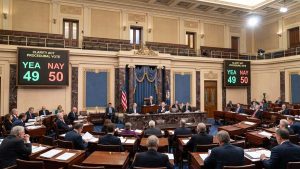
- The CLARITY Act failed to pass the Senate vote on September 15 due to disagreements between Republicans and Democrats over key points in the bill.
- The Strategy executive questioned restrictions on stablecoin rewards and the limits of the regulatory sandbox included in the proposal.
Michael Saylor addressed the debate in the crypto industry following the failure of the CLARITY Act in the United States Senate on September 15, 2026. The co-founder and chief executive officer of Strategy did not limit himself to criticizing the outcome of the vote, but instead outlined an alternative path for the crypto industry that dispenses with waiting for new legislation to move forward.
Saylor’s core proposal is straightforward: rather than accepting legislative compromises that result in unnecessary restrictions, the industry should spend the next two years deploying digital financial products under the existing regulatory framework.
His goal is to reach 50 million American users who obtain concrete benefits from those products. According to his reasoning, that user base would become a political force capable of making it considerably more difficult to reverse already-adopted innovations.
— Michael Saylor (@saylor) September 19, 2026
No Need to Wait for Congress: The Saylor Argument
Saylor noted that the version of the CLARITY agreement that came to a vote included restrictions on the rewards that providers can offer users who hold stablecoins, as well as limits on the number of employees and participating projects in the proposed regulatory sandbox.
For the executive, fixing those parameters in advance prevents the market from determining the real potential of new technologies, and protecting banks from competition is not a legitimate reason to restrict innovation.
Regulations Only Where Strictly Necessary
Instead, he argues that the SEC, the CFTC, the Treasury, and banking regulators already have sufficient tools to establish functional rules. He highlighted specific advances: the SEC’s conditional relief for tokenized equity markets and the CFTC’s work on regulated crypto trading and on-chain finance are examples of progress possible without new legislation.
His vision for the crypto industry includes Bitcoin as digital capital, STRC as digital credit, MSTR as digital equity, and USDC as digital currency, components that could be integrated to create next-generation financial services.
The 2027–2028 period is, according to Saylor, the key moment to scale those products, consolidate temporary regulatory measures as permanent rules, and seek specific legislation only where strictly necessary. Mass adoption, he concludes, raises the political cost of any future reversal.