

TL;DR
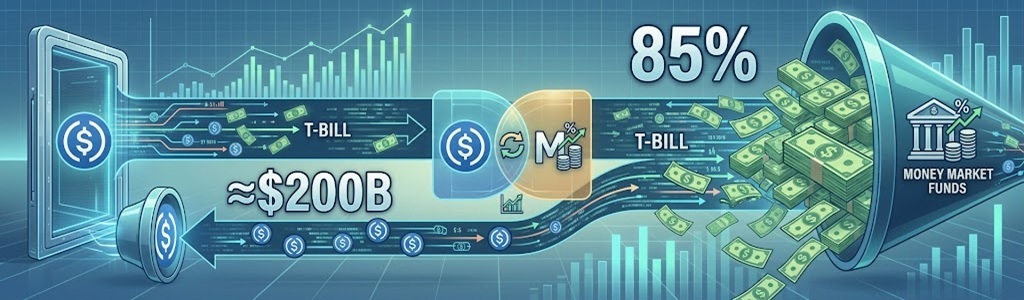
- Stablecoin issuers hold nearly $200 billion in short-term US government debt, reinforcing their growing role in Treasury markets.
- However, money-market funds absorbed about 85% of more than $550 billion in new Treasury bill supply during July and August.
- Reserve structures can also overlap, as stablecoin assets may be invested through government money-market funds and repurchase agreements.
The US Treasury said money-market mutual funds absorbed approximately 85% of more than $550 billion in additional Treasury bill supply issued during July and August. The increase represented roughly 8% growth in bill supply over two months, with traditional cash-management vehicles accounting for most of the incremental demand identified by Treasury officials.
Stablecoin issuers, meanwhile, held nearly $200 billion in Treasury bills and other short-dated government securities. That figure represents an accumulated holdings position rather than purchases during the summer issuance period, making it different from Treasury’s measurement of incremental demand. The distinction matters when assessing how much crypto-related capital directly financed the latest increase in government debt.
Stablecoins Expand Their Role In Treasury Markets
Stablecoin reserves have become increasingly connected to US government debt because issuers typically back their tokens with highly liquid assets. For crypto users, this structure links digital dollars with traditional financial markets while allowing stablecoins to remain transferable across blockchain networks.
Circle provides a clear example of how these categories can overlap. In its second-quarter filing, the company reported that approximately 84% of USDC reserves were held in the Circle Reserve Fund as of June 30. The vehicle operates as a government money-market fund, meaning some stablecoin-related Treasury exposure can appear within the broader money-fund category.
The fund’s holdings also demonstrate that reserve exposure is not limited to direct Treasury bills. Its shareholder report listed $19.111 billion in direct Treasury obligations and $46.998 billion in repurchase agreements at April 30. Those repos were collateralized by Treasuries, adding another channel through which stablecoin reserves can support demand for government securities.
Treasury Demand Spreads Across Multiple Buyers
The Federal Reserve also contributed substantial demand for Treasury bills during 2026. Treasury officials said the central bank purchased more than $300 billion through reserve-management operations and reinvestment of principal payments from agency securities. These purchases occurred in secondary markets rather than through Treasury auctions.
Foreign investors also returned to the market in July. Private foreign holdings increased by $45.0 billion, while official foreign holdings declined by $6.3 billion. Treasury data therefore show several sources of demand operating on different timelines, rather than one unified buyer group.