TL;DR
- Isabel Schnabel outlined three models for bringing central bank money onto programmable infrastructure: direct tokenized reserves, synchronized RTGS-to-DLT settlement, and privately issued tokens backed by reserves.
- Direct issuance places reserves natively onchain, while bridging leaves them in existing systems and private intermediation creates claims against reserve-backed issuers.
- The ECB’s Pontes already combines TARGET2 and DLT settlement, while Appia explores longer-term architectures intended to preserve central bank money’s wholesale settlement role.
European Central Bank Executive Board member Isabel Schnabel has outlined three ways central banks could bring settlement money onto programmable infrastructure as tokenized finance expands. In an ECB presentation, Schnabel framed the shift as part of preserving central bank money’s anchor role alongside CBDCs, tokenized deposits and stablecoins. The ECB’s three models differ mainly in who issues the onchain claim and whether reserves themselves actually move onto a distributed ledger.
Three Models Put Different Layers of Central Bank Money Onchain
The first model is direct issuance. Under this structure, the central bank operates a programmable platform where reserves are natively tokenized, giving participants direct access to central bank money on the ledger. Direct issuance places the central bank closest to the programmable settlement layer, potentially allowing tokenized reserves and financial assets to operate within the same environment rather than relying on an external bridge.
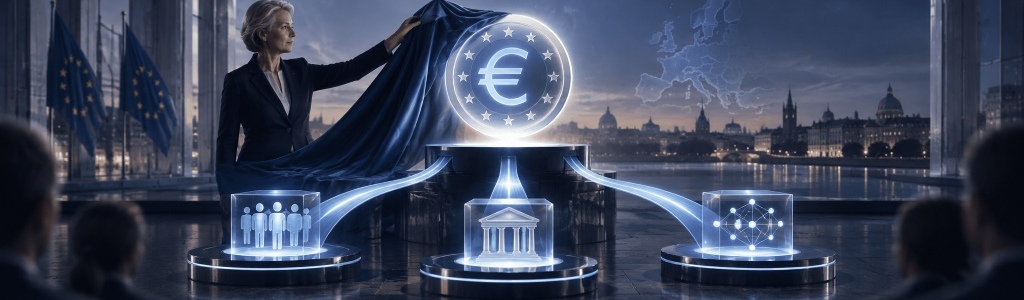
The second approach uses bridging or synchronization. Central bank reserves remain inside the existing RTGS system, while an interoperability layer connects that infrastructure with a programmable DLT platform through triggers or hash-linked mechanisms. This model keeps reserves offchain while coordinating settlement across legacy and tokenized systems, closely reflecting the logic behind Europe’s evolving tokenized settlement infrastructure without requiring a complete replacement of current payment rails.
A third model delegates tokenization to a private intermediary. The central bank continues holding reserves offchain, while an intermediary issues settlement tokens fully backed by those reserves. Those tokens remain private claims rather than direct central bank liabilities onchain. The intermediary model preserves reserve backing but introduces a private layer between users and central bank money, creating a different legal and operational structure from direct issuance.
The ECB is already combining approaches through Pontes, launched September 21 with a dual settlement model using TARGET2 or Eurosystem DLT. Planned upgrades include 24/7 availability and decentralized programmability. Pontes shows the Eurosystem is testing hybrid infrastructure rather than committing immediately to one architecture.
Longer term, Appia is exploring multiple tokenized market architectures, including unified and interconnected ledger models. Schnabel’s broader argument is that tokenization can improve programmability, atomic settlement and infrastructure integration while preserving central bank money as the ultimate settlement anchor. The strategic question is which architecture can deliver those efficiencies without weakening the two-tier monetary structure that underpins modern fiat systems.