

TL;DR:
- FinCEN formally withdrew its 2023 proposal targeting crypto mixers under Section 311 of the USA PATRIOT Act.
- The agency simultaneously rescinded the 2020 draft rule requiring identity verification for transactions involving self-custodial wallets exceeding $3,000.
- Existing compliance obligations under the Bank Secrecy Act (BSA) remain fully in force for exchanges and regulated financial institutions.
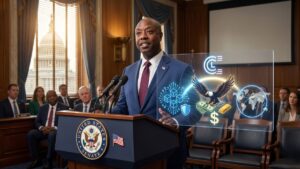
During trading hours on Monday, October 5, the Financial Crimes Enforcement Network (FinCEN) of the U.S. Department of the Treasury pulled two regulatory initiatives aimed at transactions involving crypto mixers and unhosted wallets.
The move puts an end to two rulemaking efforts that faced sustained pushback across the sector. The first initiative dates back to October 2023 and sought to designate transactions involving international convertible virtual currency mixing tools as a primary money laundering concern.
The agency noted that implementing this rule could have created a chilling effect on legitimate on-chain financial activity. Official records indicate that shelving the proposal prevents the imposition of broad reporting burdens that failed to distinguish between lawful transfers and illicit funds.
Alongside this decision, the Treasury scrapped the rule introduced in December 2020 during the Trump administration. That regulatory framework would have required banks and money services businesses to maintain counterparty records for transactions sent to private wallets exceeding $3,000, alongside mandatory reporting for transactions over $10,000.
Rollback of Requirements on Private Wallets and Privacy Protocols
The digital asset industry maintained a critical stance toward both proposals from the outset. Coinbase submitted a comment letter in January 2024 pointing out that the absence of a minimum monetary threshold in the mixing proposal would force financial institutions to report routine transactions conducted by regular users.
Industry associations argued that imposing third-party recordkeeping rules on personal wallets constituted unequal treatment when compared to traditional physical cash transactions. Market reports highlight that Section 311 of the USA PATRIOT Act had never before been applied across an entire category of transactions prior to the 2023 regulatory push.
Separately, the Treasury delivered a report to Congress in March 2026 mandated under the GENIUS Act. In that review, authorities acknowledged that privacy-enhancing protocols serve legitimate purposes for protecting personal and commercial data on public blockchains.
The rescission of these draft rules leaves existing compliance requirements unchanged. Cryptocurrency exchanges remain obligated to enforce know-your-customer controls, monitor suspicious transactions, and carry out asset freezes in accordance with sanctions lists issued by the Office of Foreign Assets Control (OFAC).
The next procedural step will be the formal publication of the withdrawal notices in the U.S. Federal Register over the coming days, which will officially conclude both administrative proceedings.